A place where economics, financial markets, and real estate intersect.

Tuesday, April 17, 2018

Morning Report: Housing starts still below demand

Vital Statistics:

Last Change
S&P futures 2698 16.25
Eurostoxx index 379.67 1.95
Oil (WTI) 66.26 0.05
10 Year Government Bond Yield 2.83%
30 Year fixed rate mortgage 4.44%

Stocks are higher this morning as China relaxes ownership restrictions on domestic manufacturers. Bonds and MBS are flat. 

We have a lot of Fed-speak today, especially in the morning. Separately, Trump announced two Fed nominees: Richard Clarida of Columbia, to be the Vice Chairman of the Fed and Michelle Bowman, previously a bank executive from Kansas. For all of his criticism of the Fed while on the campaign trail, Trump has nominated pretty much middle-of-the-fairway people to the Board. 

Housing starts came in at 1.32 million, better than expectations but still well below what is needed to meet demand. Building Permits came in at 1.35 million. Single family starts fell, while multi rose. Most of the increase was in the Midwest. 

Industrial Production rose 0.5% last month, while manufacturing production rose 0.1%. Capacity Utilization increased to 78%. So far we aren't seeing any tariff effects in the numbers.

Bank of America announced earnings yesterday, and lumped mortgage banking income into the miscellaneous "all other income" category. What an ignominious end to Countrywide. Bank earnings season continues.

Independent mortgage bankers saw profit per loan get cut in half last year as refis dried up and the business got more competitive. Refis fell from 36% of all origination volume to 25%. 

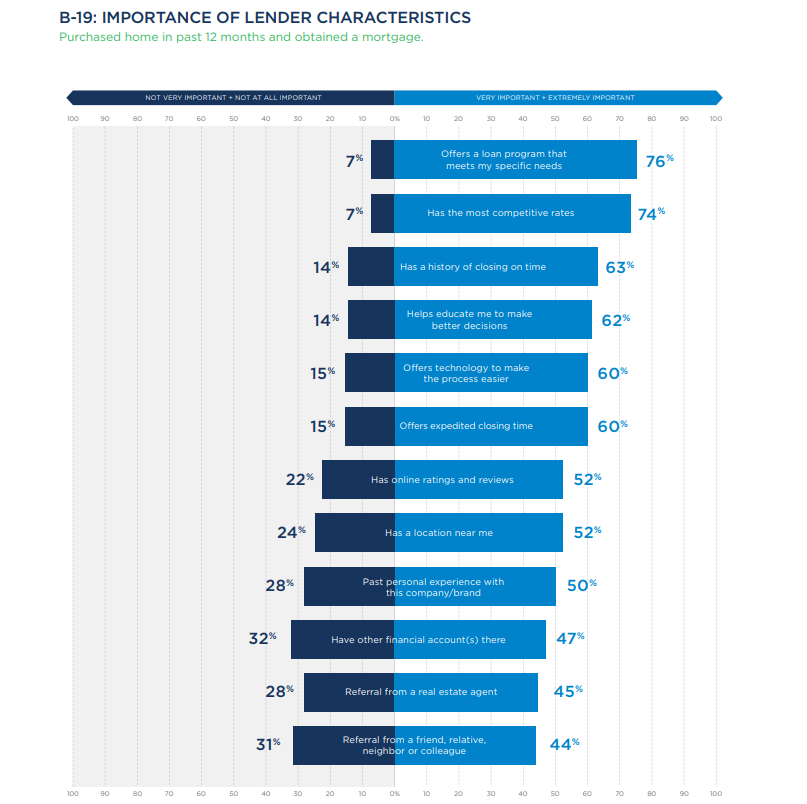
Zillow crunched the numbers and looked at the typical homebuyer in 2017. The typical buyer is 40 years old, making 87k. Millennials make up 42% of the cohort. They typically spend about 4.3 months finding a home. Interestingly, despite the size of the investment, most homebuyers only contacted 1 lender. Here is what is important to homebuyers when thinking about a lender:

The median home was sold in 81 days, and that includes the closing process. This means the typical home was on the market for only 1 month. This is 8 days faster than 2016. 

The National Low Income Housing Coalition has a new report showing how acute the housing shortage is at the low end. Only 35 affordable and available rental homes exist for every 100 extremely low income renter households. Rising home prices and mortgage rates are reducing affordability, however interest rates are still extremely low historically. In the early 80s, a the first year's mortgage payment consisted of 99% interest, 1% principal. 

The IMF forecasts that global growth will hit 3.9% this year, the fastest since 2011, driven by emerging Europe, and the US. 

Monday, April 16, 2018

Morning Report: Zillow gets slammed after changing its business model

Vital Statistics:

Last Change
S&P futures 2672 14
Eurostoxx index 378.3 -0.91
Oil (WTI) 66.56 -0.84
10 Year Government Bond Yield 2.87%
30 Year fixed rate mortgage 4.44%

Stocks are higher despite coordinated strike in Syria over the weekend. Bonds and MBS are down. 

Watch the oil markets. North Sea Brent crude is rising on tensions in the Middle East, but West Texas Intermediate (which is the main oil used in the US) is shrugging off the news. Bullish bets on Brent oil have hit record highs. 

The 2 year hit 2.4%, the highest level since 2008. The flattening of the US yield curve continues. 

There isn't much in the way of market-moving data this week, although we will get a lot of Fed-speak. Probably the biggest one will be housing starts tomorrow. 

Retail sales rose 0.6% in March, which was better than the Street 0.4% consensus. The control group increased by 0.4%, a touch below the 0.5% consensus estimate. Gasoline sales were up on higher prices. Revisions were lower, however. 

Business activity in New York State decelerated last month according to the Empire State Manufacturing Survey. New Orders and Production slowed down somewhat, but employment remained firm and the workweek increased. Future sentiment declined to the lowest level in 2 years.

The NAHB / Wells Fargo Housing Market Index slipped last month, but builder sentiment remains strong. 

Wells Fargo faces $1 billion in fines due to force-placed auto insurance and improper charges for lock extensions. The big banks have all reported strong earnings, and the tax law changes are certainly helping. 

Zillow shares fell 9% on news they plan to get into the house flipping business. "We're entering that market and think we have huge advantages because we have access to the huge audience of sellers and buyers," Zillow CEO Spencer Rascoff said on CNBC's "Squawk Alley." "After testing for a year in a marketplace model, we're ready to be an investor in our own marketplace." Investors are understandably skeptical, as the multiple for a fintech company is much higher than one for a property company, and it puts Zillow in direct competition with the realtors who utilize the site. Investors are not wild about changing focus from an ad model with high margins and low balance sheet usage to one that is low margin and uses a lot of balance sheet. Another issue: will people trust Z-scores if the company has a financial interest in the value of real estate in a particular area?

Want to know how acute the housing shortage is in California? From 2000 - 2015, the state built 3.4 million too few homes to keep up with job, population, and income growth. That is over 2 year's worth of current housing starts for the whole US population. Pretty astounding when you consider those years start before the housing bubble really got going. CA has always had NIMBY issues, and now there is a push to allow dense multi-family building near public transit, even if local zoning codes prohibit it. Separately, it looks like Dodd-Frank regulations did have an adverse affect on smaller banks. I wonder how much that plays into the housing shortage. 

Speaking of CA housing, here is what you can get for $800,000 in San Jose. Handyman special. 

Friday, April 13, 2018

Morning Report: Wells reports flat YOY growth in origination

Vital Statistics:

Last Change
S&P futures 2676 12.5
Eurostoxx index 380.54 1.72
Oil (WTI) 66.97 -0.24
10 Year Government Bond Yield 2.83%
30 Year fixed rate mortgage 4.42%

Stocks are higher after it looks like cooler heads are prevailing in a trade war with China. Bonds and MBS are down. 

Donald Trump told his aides to explore re-joining the Trans-Pacific Partnership trade deal after withdrawing early in his administration. Does this mean "re-negotiate?" Unclear, but that would encounter heavy resistance. Still, it is better than throwing around tariff threats. Markets are breathing a sigh of relief. 

Job openings were little changed at 6.1 million in February. They are up almost 8% YOY however. The quits rate was stuck at 2.2%. The quits rate is a metric the Fed invariably mentions in their analysis of the job market and wage inflation. A higher quits rate usually presages wage inflation. Construction and manufacturing had big increases in openings. 

Consumer sentiment slipped in the preliminary April reading. Market volatility could be driving it, however higher gas prices could be playing a role as well. 

Acting CFPB Head Mick Mulvaney appeared before the Senate Banking Committee yesterday, and noted that Dodd-Frank only requires him to appear, not answer questions. Jeb Hensarling made a crack about the Chairman could sit and play Candy Crush in front of Congress if he wanted to. Mulvaney did answer questions, however he was making a point about how little accountability the agency has, and perhaps a point from his memo earlier - that the CFPB would follow the law, but go no further. The big question for the CFPB is the status of the PHH case. If that goes to SCOTUS, the only one that has standing to defend the agency is the Administration. 

Wells Fargo reported earnings, and it looks like they have been affected less by higher rates than other independent bankers. Mortgage origination was down 19% QOQ, which is simply seasonality at work, but they were only down 2% YOY. As you would expect, the purchase business is a higher percentage, and it looks like they were able to maintain flat YOY growth by getting more aggressive in the correspondent channel. The price of that was a sizeable drop in margins - 31 basis points. 

JP Morgan saw a more typical drop, with originations down 19% YOY. The servicing portfolio fell as well. Citi reported better earnings on equity trading. 

Californians may get to vote for a divorce from each other - to separate the state into 3 separate ones. One will contain the coast between LA and SF, another will be Northern CA, and the other will be Southern CA. As of now, LA and SF basically control the whole state, and there is a big conflict between the coastal environmental types and the farmers who supply something like half of the US's agricultural output. Still, given that Democrats control the state and the ag belt will probably vote R, this probably isn't happening. 


Thursday, April 12, 2018

Morning Report: Minutes offer clues why the Fed keeps missing on inflation

Vital Statistics:

Last Change
S&P futures 2355.5 14.5
Eurostoxx index 377.42 1.23
Oil (WTI) 66.58 -0.24
10 Year Government Bond Yield 2.80%
30 Year fixed rate mortgage 4.39%

Stocks are rising this morning on no real news. Bonds and MBS are down. 

While investors are still worried about conflict in Syria, things seem to be settling down somewhat as Russia seemed to cool their rhetoric and Trump backed off from suggesting an attack was imminent. Call it WWE diplomacy: lots of trash-talking outside the ring, which often leads nowhere. 

The last of the 3 inflation indicators this week came in lower than expected. Import prices were flat month-over-month and rose 3.6% YOY. Import prices are driven by the currency and commodity prices, so the Fed tends to de-emphasize them.  

Initial Jobless Claims fell to 233,000 last week. The labor market continues to shrug off the volatility in the markets. 

The FOMC minutes didn't really reveal much we don't already know, however one statement stuck out. On the labor market, they mentioned that the labor force participation rate was stronger than they had expected. That is interesting because the conventional wisdom in the markets and Washington is that the labor force participation rate is too low. The implications of that view - that the labor force participation rate should be lower - means that their inflation forecasts going forward might be too high. They are forecasting the unemployment rate to fall lower, which would in theory trigger more wage inflation (companies fighting for fewer workers), and push the Fed to hike rates faster in response. If they are getting the forecasts wrong for the labor force participation rate, it means that (a) they have more room to let the economy run, and (b) the longer-term growth rate of the economy is higher. This is good news. Perhaps it is a realization that fewer people are retiring at 65, and many of those longer-term unemployed are returning to the labor force. The labor force participation rate acts as sort of a speed limit for the economy. As it rises, the speed limit rises as well. 

With regard to trade, this is what they had to say: "Participants did not see the steel and aluminum tariffs, by themselves, as likely to have a significant effect on the national economic outlook, but a strong majority of participants viewed the prospect of retaliatory trade actions by other countries, as well as other issues and uncertainties associated with trade policies, as downside risks for the U.S. economy." In other words, the trade war has to really escalate for it to register economically. 

Mick Mulvaney laid out his vision for the CFPB in his semiannual testimony to Congress yesterday. His prepared remarks are here. As he alluded to earlier, things are changing: "The Bureau is going about its work in several new ways. First, to execute the new mission, the Bureau will continue to seek the counsel of others and make decisions only after weighing relevant available evidence and a full range of perspectives. Second, the Bureau will protect the legal rights of all, equally. And third, we will do what is right with confidence, acting with humility and moderation." On enforcement, he said: In another change, the Bureau practice of “regulation by enforcement” has ceased. The Bureau will continue to enforce the law. That is our job, and we take it seriously. However, people will know what the rules are before the Bureau accuses them of breaking those rules. Finally, he stated that the CFPB will review the Home Mortgage Disclosure Act and recommend changes.

CoreLogic notes that we have yet to see any effects of the new tax regime on home price appreciation. It is still early, however. That said, we do have a lot of inventory at the higher price points - probably most of it was driven by building decisions over the past several years - however tax reform is certainly not helping, at least in the high price / high tax MSAs. 

Wednesday, April 11, 2018

Morning Report: Inflation comes in lower than expected

Vital Statistics:

Last Change
S&P futures 2632.25 -22.75
Eurostoxx index 375.86 -2.56
Oil (WTI) 66.25 0.74
10 Year Government Bond Yield 2.77%
30 Year fixed rate mortgage 4.43%

Stocks are lower this morning on tensions in the Middle East. Bonds are up on the risk-off trade.

In political news, House Speaker Paul Ryan will not run for re-election. 

Inflation came in lower than expected in March, falling 0.1% MOM and rising 2.4% YOY. Ex-food and energy, the index rose 0.2% MOM and 2.1% YOY. Bonds are breathing a sigh of relief on the number. 

We will get the minutes from the March FOMC meeting today at 2:00 pm. They usually aren't market-moving, but just be aware. Since this is Jerome Powell's first meeting as head of the FOMC, it might be parsed a little more closely than usual. 

Mortgage applications fell 2% last week, as both refis and purchases fell by the same amount. This was in spite of a 3 basis point drop in the typical 30 year fixed mortgage rate. Refis are at their lowest level in a decade. Refi activity is going to be driven more by home price appreciation these days.

Luxury homes are taking longer and longer to sell, and are trading at bigger discounts to the asking price. This is especially acute in high tax states like New York, where there is an absolute glut of homes above $1 million. Part of it is simple over-pricing. The homes that sat on the market for over 180 days went for 71% of asking price, while homes that went in under 180 days got 93% of the asking price.

The CFPB released its annual review of consumer complaints, and credit / consumer reporting topped the list, which is unsurprising given the Equifax data breach last year. Debt collection was the next biggest issue, followed by mortgages. Richard Cordray's bugaboo - payday lending - failed to garner even 1% of complaints. This is what Mick Mulvaney was referring to when he said "data will drive our decisions."

Rising home prices relative to incomes are pushing up debt to income ratios, which is why this Spring Selling Season is shaping up to be the worst in years. Part of the problem was alluded to above - a dearth of inventory at the low end of the price scale and a glut at the high end.

City grind got you down and you are thinking of moving to the country? Here are some things to consider..

A record 64 million Americans (or about 20%) live in multi-generational households. This is largely driven by younger adults who continue to live with their parents. The ratio bottomed in 1980 and has been moving steadily upward ever since. 

Tuesday, April 10, 2018

Morning Report: Markets recover on soothing trade statements out of China

Vital Statistics:

Last Change
S&P futures 2647 28.75
Eurostoxx index 376.97 1.67
Oil (WTI) 64.76 1.34
10 Year Government Bond Yield 2.79%
30 Year fixed rate mortgage 4.41%

Stocks are up big after Chinese President Xi Jinping made a speech that emphasized dialogue and opening up the Chinese markets. Bonds and MBS are flat. 

In a speech to the Boao Forum, Chinese President Xi Jinping warned against returning to a "Cold War mentality" and pledged to make progress on imports, foreign ownership limits, and intellectual property. This have always been the sticking points with the Chinese, and while they may just be empty words, they are being taken optimistically this morning. 

Inflation at the wholesale level increased in March, as the PPI came in a little higher than expected. The headline number rose 0.3%, while the core rate rose 0.4%. Higher metals prices (in response to tariff announcements) drove the increase. 

Small Business Optimism remains in the top 5% historically, according to the NFIB. Lower taxes are driving the increase in sentiment. Improved earnings were the second best reading in 30 years. Biggest problem: Quality of Labor. In fact, 21% of all respondents considered the inability to find qualified labor their biggest headache. A net 33% reported increasing compensation, the highest number since 2000. Perhaps we might start seeing a bit of a move in wage inflation, however the biggest predictor of wage inflation - the quits rate - hasn't gone anywhere in years. We'll get an update on the quits rate Friday. 

The CFPB has initiated no enforcement actions since Mick Mulvaney took over, according to consumer advocates. Prior CFPB Chairman Richard Cordray preferred to "regulate by enforcement action" which is the more aggressive approach to take with banks. Mick Mulvaney, in a memo to his staff, promised to end the Bureau's pattern of "pushing the envelope" and "looking for excuses" to bring lawsuits. The enforcement action is one of two ways for the Bureau to regulate - the other is via supervisory means - in other words confidential discussions with the banks involved. Richard Cordray preferred to use only the enforcement action, which the industry disliked. The best analogy would be driving down an expressway with no speed limit signs. The only way to find out if you are going over the limit is when you (or someone else) gets a ticket. Regulators generally loathe to put out "bright lines" for fear that the industry will go right up to the line, and then figure out how to game it. Mulvaney is backing off from that approach. 

That said, as any compliance officer can tell you, the CFPB is the not only agency to worry about. The individual states also have jurisdiction and can do much of what the CFPB did. New Jersey (one of the most creditor-unfriendly states out there) has just set up its own version of the CFPB, nominating ex-DiBlasio attorney Paul Rodriguez to run the Director of Consumer Affairs. "Rodriguez’s selection highlights the Administration’s efforts to fill the void left by the Trump Administration’s pullback of the Consumer Financial Protection Bureau (CFPB), fulfilling one of Governor Murphy’s promises to create a “state-level CFPB” in New Jersey."

Perhaps due to the increased regulatory scrutiny in DC (and elsewhere) big banks are getting back in the subprime business, although they are doing it indirectly. Big bank loans to non-bank financial firms in the business of subprime auto, etc are up sixfold since 2010. For example, Exeter, which does sub-600 FICO auto loans is owned by Blackstone and has a line of credit from Wells and Citi.

Delinquencies remain elevated in areas hit hard by the hurricanes, but early stage delinquencies are back to normal levels, according to CoreLogic. The 30+ DQ rate came in at 4.9% in January, down 0.2% YOY. The foreclosure rate fell to 0.6% from 0.8% a year ago. 

Homebuyer sentiment rebounded in March, according to the Fannie Mae Home Purchase Sentiment Index. Of course people may want to buy, but there isn't much around in the way of inventory. Overall, people are reasonably optimistic on the economic front as well. 


Monday, April 9, 2018

Morning Report: Corporate credit spreads are widening

Vital Statistics:

Last Change
S&P futures 2621 15.3
Eurostoxx index 375.48 0.66
Oil (WTI) 62.54 0.48
10 Year Government Bond Yield 2.79%
30 Year fixed rate mortgage 4.43%

Stocks are up to start the week after a pretty lousy session on Friday. Bonds and MBS are flat.

The week after the jobs report is usually pretty data-light, however we will get the Producer Price Index and the Consumer Price Index on Tuesday and Wednesday. 

Friday's jobs report should allay investor fears that the Fed is behind the curve, at least according to PIMCO's Mohammed El-Arian. The light payroll number was probably weather-driven and the 3 month average is around 200k, which is solid and respectable. Wage growth came in as expected. Investors should take comfort that the Fed is probably not at risk of making a policy mistake due to an overheating economy. His view is that there is a 65 / 35 percent chance the Fed will stick the landing, meaning that economic growth will continue to more broadly expand and that markets will adapt to the higher volatility associated with normal monetary policy.

An example of higher volatility: corporate bond spreads. The end of 2017 was characterized by extremely low volatility in the stock and bond markets. When volatility falls, risk premiums contract. We saw corporate credit spreads reach pre-crisis levels. Since the beginning of the year, they are back to widening. Bad news for corporate bond funds, which have been beset by widening spreads and higher rates. 


The story of the past couple of years has been "subprime auto." The chickens are coming home to roost on this trade, and we are starting to see some subprime auto finance companies go bankrupt. Indeed, when you talk about the effects of low volatility in the market, things like this come to mind. With rates being held down by Fed actions, investors inevitably reach for yield. For a while, you could get a lower rate on a 6 year auto loan than you could on a 30 year fixed rate mortgage. This is insane when you take into account that the value of the collateral underlying a mortgage is 90% sure to increase over time, while the value of the collateral underlying the car loan is 100% sure to depreciate over time. That said, this won't be a repeat of 2008 economically. 

Mortgage credit got tighter in March, according to the MBA's Mortgage Credit Availability Index. It was most pronounced in government lending, which could have been explained by some of the weakness and illiquidity we were seeing in the higher coupon Ginnie securities. Ginnie investors have been burned by higher prepay speeds and have been reluctant to buy the higher coupon securities. This makes the higher note rates (which is where the lower credit scores usually reside) cut off from the rest of the market.