A place where economics, financial markets, and real estate intersect.

Tuesday, March 11, 2014

Morning Report - Sentiment remains in hibernation

Vital Statistics:

Last Change Percent
S&P Futures  1878.7 1.5 0.08%
Eurostoxx Index 3094.6 1.8 0.06%
Oil (WTI) 100.7 -0.4 -0.43%
LIBOR 0.233 -0.001 -0.45%
US Dollar Index (DXY) 79.85 0.081 0.10%
10 Year Govt Bond Yield 2.78% 0.00%  
Current Coupon Ginnie Mae TBA 105.7 0.0
Current Coupon Fannie Mae TBA 104.3 0.0
RPX Composite Real Estate Index 200.7 -0.2
BankRate 30 Year Fixed Rate Mortgage 4.36

Markets are flattish this morning on no real news. Bonds and MBS are unchd.

The NFIB Small Business Optimism Report showed sentiment took a hit in February, falling from 94.1 to 91.4. January's big hiring plans seem to have been reversed. Aside from a plan to increase capital expenditures, there is not a lot to hang your hat on in this report. Small business sentiment remains firmly mired at recessionary levels, which is astounding when you consider the S&P 500 is at record levels.


Future expectations of home price appreciation took a step upward in February, according to Fannie Mae. Homeowners expect to see 3.2% home price appreciation over the next 12 months, which was a step up from January's 2% reading. 56% expect mortgage rates will increase over the next 12 months, while 33% expect them to be flat. 


And finally, given the theme of sentiment, economic confidence is waning, according to Gallup. This probably doesn't bode well for retail sales data coming out on Thursday. It is possible that weather is impacting this number, as it seems to have been blamed for everything else, but it is a bad omen for a 2H acceleration, which everyone seems to be forecasting. 


Monday, March 10, 2014

Morning Report - Slow news week

Vital Statistics:

Last Change Percent
S&P Futures  1875.0 -3.1 -0.17%
Eurostoxx Index 3104.7 9.4 0.30%
Oil (WTI) 101.4 -1.2 -1.17%
LIBOR 0.234 -0.001 -0.55%
US Dollar Index (DXY) 79.74 0.024 0.03%
10 Year Govt Bond Yield 2.78% 0.00%  
Current Coupon Ginnie Mae TBA 105.5 0.0
Current Coupon Fannie Mae TBA 104.2 0.0
RPX Composite Real Estate Index 200.7 -0.2
BankRate 30 Year Fixed Rate Mortgage 4.37

Markets are lower on no real news. Bonds and MBS are flattish.

We have a data-light week coming up, with nothing today, and then a few reports that aren't really market moving. The biggest one will probably be retail sales on Thursday.

Man Bites Dog:  CFPB is guilty of discrimination under the disparate impact theory.

The NAHB Leading Markets index shows that 59 out of 350 metro areas returned to or exceeded their last normal levels of economic and housing activity. This index is based on housing and jobs activity. Overall, the nation is running at 87% of normal economic and housing activity. 


Professional Investors have been driving up the price of housing in some areas to unaffordable levels. We are seeing that happen in South Florida, and probably Southern California as well. Which begs the question: What is their exit strategy? 

Friday, March 7, 2014

Morning Report - Decent jobs report

Vital Statistics:

Last Change Percent
S&P Futures  1886.3 10.0 0.53%
Eurostoxx Index 3146.7 2.2 0.07%
Oil (WTI) 102.1 0.5 0.49%
LIBOR 0.236 0.001 0.23%
US Dollar Index (DXY) 79.75 0.090 0.11%
10 Year Govt Bond Yield 2.80% 0.06%
Current Coupon Ginnie Mae TBA 105.7 0.0
Current Coupon Fannie Mae TBA 104.1 -0.3
RPX Composite Real Estate Index 200.7 -0.2
BankRate 30 Year Fixed Rate Mortgage 4.39

Markets are higher after a stronger-than-expected jobs report. Bonds and MBS are getting slammed.

Data Dump from the jobs report
  • Feb payrolls up 175k (149k exp)
  • Two month revision 25k
  • Unemployment rate ticks up to 6.7% 
  • Average Hourly earnings up .4% (.2% expected)
  • Average weekly hours dropped to 34.2
  • Labor force participation rate steady at 63%
The tick up in the unemployment rate means that discouraged workers are beginning to start looking for jobs again. Overall, it was a decent report. It won't change the Fed's posture by any means, but it shows the labor market is gradually becoming more balanced.

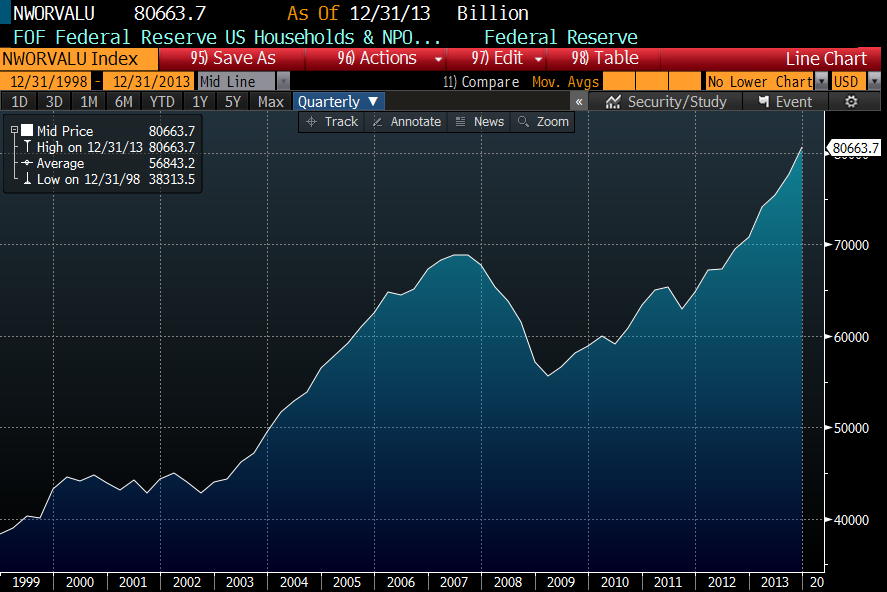
Yesterday, we got the household net worth numbers out of the Fed. Net worth increased almost 4% quarter-over-quarter and 14% year-over-year. This shows a lot of the Great American Deleveraging is behind us. 


One thing to keep in mind however, is that this increase in net worth has been driven primarily by asset price inflation. If you look at aggregate household debt over the same period, it has fallen, but not dramatically.


What this shows is that it is imperative that the Fed stick the landing with respect to exiting QE and normalizing interest rates. If asset prices (houses, stocks) fall as rates increase, it will undo a lot of the progress that has been made, and will probably be recessionary. 

Thursday, March 6, 2014

Morning Report - Slow news day

Vital Statistics:

Last Change Percent
S&P Futures  1876.6 4.2 0.22%
Eurostoxx Index 3140.8 4.9 0.15%
Oil (WTI) 101 -0.5 -0.45%
LIBOR 0.235 0.001 0.30%
US Dollar Index (DXY) 79.87 -0.244 -0.30%
10 Year Govt Bond Yield 2.73% 0.03%  
Current Coupon Ginnie Mae TBA 105.7 -0.1
Current Coupon Fannie Mae TBA 104.4 -0.1
RPX Composite Real Estate Index 200.7 -0.2
BankRate 30 Year Fixed Rate Mortgage 4.33

Slow news day. Markets are higher this morning on a mixed bag of economic data. Bonds and MBS are down.

A few economic data points this morning: Challenger and Gray announced job cuts fell 24%, productivity was revised downward from 2.2% to 1.8% and initial jobless claims fell to 323k. Unit Labor costs were revised to -.1% from -.5%. Given what we saw in the personal income numbers - that pretty much all of the increases in income were due to increased transfer payments - it looks like costs are increasing without any corresponding increase in output - a recipe for stagnant wages.

Junk Bond King Michael Milken has a good editorial about the unintended consequences of government meddling in the housing market, the biggest one was the housing bubble. 

Speaking of unintended consequences, the unpopularity of obamacare is proving to be a big one for Democrats. The Administration has decided to delay rules prohibiting high deductible insurance plans until after the midterm elections and through 2015. Of course this will ensure that obamacare will remain a battleground issue for 2016. 

Wednesday, March 5, 2014

Morning Report - ADP signalling a weak jobs report this Friday

Vital Statistics:

Last Change Percent
S&P Futures  1872.1 0.5 0.03%
Eurostoxx Index 3135.9 -0.5 -0.01%
Oil (WTI) 102.9 -0.4 -0.41%
LIBOR 0.234 -0.001 -0.40%
US Dollar Index (DXY) 80.24 0.067 0.08%
10 Year Govt Bond Yield 2.70% 0.01%  
Current Coupon Ginnie Mae TBA 105.6 -0.1
Current Coupon Fannie Mae TBA 104.5 0.0
RPX Composite Real Estate Index 200.7 -0.2
BankRate 30 Year Fixed Rate Mortgage 4.32

Markets are flat this morning as Ukranian Euphoria meets a putrid ADP jobs report. Bonds and MBS are flat, after bonds cratered yesterday, with the 10 year yield trading to 2.7% from 2.6%. 

The ADP jobs report came in at 139k, much lowers than the estimate of 155k. More importantly, January was revised downward form 175k to 127k. The first impulse is to blame the weather, but construction increased 14k. Manufacturing was flat, and (you guessed it) financial services fell. Friday's payroll estimate is 150k, which now seems high. N.B. - ADP has been a pretty lousy predictor of the BLS number lately, so keep that in mind. FWIW, Mark Zandi of Moody's believes weather is playing a part here, which is creating some pent-up demand for workers. He is calling for some 250k prints in the Spring. 

Last week's flight to safety bond market rally, helped increase mortgage applications by 9.4%. Both purchase and refi apps rose the same amount. The indices also benefited from an easy comparison with the holiday shortened prior week. The average 30 year fixed rate mortgage fell from 4.53% to 4.47% last week. Refis as a percent of all loans fell to 57.7%.

The FHA insurance fund will have a positive capital reserve balance at the end of 2014 and will not require a draw from the U.S. Treasury. FHA is asking for authority to collect an additional administrative fee, which will undoubtedly annoy affordable housing advocates who are pressing FHA to reduce fees. This fee may be part of the White House's 2015 budget, which is DOA.

First time homebuyers continue to struggle with tight credit and competition from professional investors. Until the first time homebuyer comes back to the market, the housing recovery (and the mortgage business itself) will be fragile. This also speaks to the completely bifurcated credit markets out there. While credit to consumers is still tight, banks are throwing money at private equity firms and institutional investors. 

It has gotten so bad that private equity firms are outbidding strategic buyers in industrial mergers, which is astounding when you consider that strategic buyers have the benefit of synergies and private equity firms do not. Historically, private equity firms were the ones who would swoop in to buy assets on the cheap; now they are winning bidding wars. 

This speaks to a theme I have been discussing for a while - the stock market is at or near record highs, and yet the broader economy is in a completely different place. Corporate America is flush with cash, and wages / hiring are flat. Ironically, the cash they have will probably be spent on productivity enhancing CAPEX, which will be good for stocks, but not necessarily good for wages. Consumption and wage growth are currently correlating at 95%, when that number has been closer to 50%. So, when you have about 2% wage growth, you get about 2% GDP growth. Which accounts for this kind of "meh" recovery we have had.

Tuesday, March 4, 2014

Morning Report - Home prices increase 12% year over year

Vital Statistics:

Last Change Percent
S&P Futures  1861.7 18.6 1.01%
Eurostoxx Index 3120.2 66.2 2.17%
Oil (WTI) 103.9 -1.0 -0.97%
LIBOR 0.235 0.000 -0.13%
US Dollar Index (DXY) 79.94 -0.137 -0.17%
10 Year Govt Bond Yield 2.64% 0.04%  
Current Coupon Ginnie Mae TBA 106.1 -0.2
Current Coupon Fannie Mae TBA 104.9 -0.2
RPX Composite Real Estate Index 200.7 -0.2
BankRate 30 Year Fixed Rate Mortgage 4.32

The market giveth, the market taketh away. Stocks are up (and bonds / MBS are down) on positive developments in the Ukranian situation. Expect more of the same until the situation resolves itself. LOs, be sure to explain to your borrowers that rates will be very volatile for the near future and floating is playing with fire. 

Home prices rose .9% month over month and 12% year-over-year in January, according to Corelogic. Prices remain 17.3% below their peak in April 2006. We had seen a bit of a divergence between the indices, with Case-Shiller observing month-over-month decreases (would signal a flattening of the index) and FHFA still reporting month-over-month increases. CoreLogic's numbers suggest Case Shiller is the outlier. 

Obama is set to unveil his new budget today, which will increase spending and taxes. This is a political document, meant to frame the debate for midterm elections this year. It has absolutely zero chance of being implemented

Speaking of political acts, if you like your health care plan, you can keep it (at least through midterms). Obama is planning to delay another part of obamacare, which forbids non-compliant insurance policies until after the midterm elections. Side note, obamacare accounted for the big increases we saw in yesterday's personal incomes and personal spending report.

Monday, March 3, 2014

Morning Report - International Tensions take center stage

Vital Statistics:

Last Change Percent
S&P Futures  1841.3 -16.3 -0.88%
Eurostoxx Index 3069.1 -80.1 -2.54%
Oil (WTI) 104.6 2.0 1.95%
LIBOR 0.236 0.000 0.00%
US Dollar Index (DXY) 79.85 0.157 0.20%
10 Year Govt Bond Yield 2.61% -0.04%  
Current Coupon Ginnie Mae TBA 106.2 0.0
Current Coupon Fannie Mae TBA 105 0.1
RPX Composite Real Estate Index 200.7 -0.2
BankRate 30 Year Fixed Rate Mortgage 4.31

Stocks are weaker and bonds are stronger on developments in Ukraine. While this situation should not have much of a direct impact on the US, it will push rates lower at the margin on the flight to safety trade. Equities will be vulnerable to the risk on trade.

Personal Income and Personal spending came in much better than expected in January. Incomes increased .3%, while spending increased .4%. December spending was revised downward from .4% to .1%. The PCE core index came in at .1%. 

The Markit US PMI came in at 57.1, a little better than expected, while the ISM indices were stronger as well. Construction spending rose .1%, which again was better than expected. 

We have a lot of data this week, culminating with the jobs report on Friday. The other big report will be the ISM surveys. That said, geopolitical concerns will probably drive the bond market more than the data will. 

The Hardest Hit Fund money (that was intended to be used to modify mortgages and help homeowners in distress) is now being used to demolish homes. In Detroit alone, 70,000 homes (or 19% of the total inventory) may need to be torn down. It may turn out that much of the shadow inventory is stuff that really isn't going to affect supply because it is unsaleable.