A place where economics, financial markets, and real estate intersect.

Tuesday, April 10, 2012

Morning Report


Vital Statistics:
Last Change Percent
S&P Futures 1377.0 2.1 0.15%
Eurostoxx Index 2359.4 -33.1 -1.38%
Oil (WTI) 102.05 -0.4 -0.40%
LIBOR 0.4692 0.000
0.00%
US Dollar Index (DXY) 79.863 0.130 0.16%
10 Year Govt Bond Yield 2.05% 0.00%

RPX Composite Real Estate Index 170.57 0.0

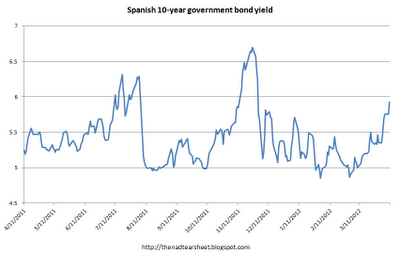
Markets are generally weaker as Europe plays catch-up with the US markets. US bonds and MBS are flat. Spanish yields are 17 basis points higher on no major economic news. An unexpected drop in imports pushed the Chinese trade balance into a surplus and is flashing warning signs about Chinese domestic demand.

With Greece temporarily off the front pages, all eyes turn to Spain. The new Spanish government is determined to implement austerity measures and reduce the budget deficit by almost 2/3 in 2013. Spain had a massive property bubble, which has weakened their banking system considerably. The banks are thought to be marking their real estate portfolios and mortgage bonds at unrealistic levels.

One powerful method of clearing the excess housing inventory is the short sale, and often times it is a lengthy, painful process as banks and other creditors drag their feet, hoping for better prices. Senator Sherrod Brown (D-OH) has introduced legislation to force banks to make a decision within 75 days of a request from a homeowner.

Bloomberg has been tracking a story about J.P. Morgan's massive credit default swap positions in their Treasury department, which is raising questions about Dodd-Frank and proprietary trading versus hedging. The trader, Bruno Iksil, has been selling protection on an index of investment-grade bonds (Markit CDX North America Investment Grade Series 9) and is thought to have sold $100 billion worth of protection on the index. This is the trade that blew up AIG and I cannot imagine what it possibly could be hedging. As a bank, JP Morgan generally makes loans so it makes money if US corporations generally do well, and poorly when US corporations don't do well. Selling protection is the exact same bet. The article goes on to speculate that this may be part of a spread trade, but even then a spread trade is a speculative position, not a hedge. Anyway, regulators and politicians seem to be lining up against this trade, and if JP Morgan is forced out, they will undoubtedly pay dearly to exit.

Chart: Spanish 10-year government bond yields

Monday, April 9, 2012

Morning Report

Vital Statistics:
Last Change Percent
S&P Futures 1374.7 -15.5 -1.11%
Eurostoxx Index 2392.5 -5.9 -0.25%
Oil (WTI) 101.65 -1.7 -1.61%
LIBOR 0.4692 0.000 0.00%
US Dollar Index (DXY) 79.92 0.034 0.04%
10 Year Govt Bond Yield 2.03% -0.02%
RPX Composite Real Estate Index 170.61 -0.1

Slow news day.

Equity futures are lower on the back of Friday's lousy employment report. Bonds and MBS are rallying, with the 10-year again flirting with t a 2% yield. European markets are closed for the Easter holiday, so volumes will be light.

Friday's employment report showed an increase of 120,000 private sector jobs and a drop in the unemployment rate to 8.2%. The reason for the drop in unemployment was due to a drop in the labor force participation rate, which has fallen from 64% to 63.8% since December. These are the 99-ers who have exhausted their unemplyment benefits and no longer count as part of the labor force.

Alcoa kicks off Q1 earnings season tomorrow after the close

Thursday, April 5, 2012

Mourning Report

RIP Jim (Guv'nor) Marshall - the man who made heavy guitar sound so awesome

Vital Statistics:

LastChangePercent
S&P Futures 1388.0-5.2-0.37%
Eurostoxx Index2373.3-25.1-1.05%
Oil (WTI)101.660.20.19%
LIBOR0.46920.0000.00%
US Dollar Index (DXY)80.0460.2680.34%
10 Year Govt Bond Yield2.16%-0.06%
RPX Composite Real Estate Index170.920.3

Markets are continuing the sell-off that began when the Fed hinted that QEIII isn't going to happen. Bonds are up over a point and MBS are up half a point. Euro sovereign yields are wider again, and you are starting to see bids in bank credit default swaps, particularly in some of the traditional European ne'er do wells - Dexia and Intesa SanPaolo. Spain is the new one to watch.

Today is the first Thursday of the month, which means retailers are reporting same store sales for March. Generally, they appear to be strong, particularly in department stores and Men's / Women's apparel. Discounters and Teen Apparel were weaker with some exceptions (Zumiez and Target). Overall, the numbers look good and a few took up Q1 earnings estimates. The "yes. but..." is that March had some unseasonably warm weather, and that undoubtedly helped get people out of the house and into the stores.

Initial Jobless Claims came in at 357k. Continuing Claims were 3,338k.

REO asset managers may want to watch this developing situation - allegations of discrimination regarding the maintenance and upkeep of homes in minority neighborhoods. The National Fair Housing Alliance put out a report alleging that REO properties in predominantly minority neighborhoods lack "for sale" signs, have boarded-up windows, and trash, as opposed to REO in white neighborhoods. This study was put out with a grant from HUD and will undoubtedly be fodder for a lawsuit.

The US is far behind on reforming the country's housing finance system, Geithner said at a speech at the Chicago Economic Club. The reality is that our current housing finance system is more or less nationalized and we are far from being in the position to have private capital carry the load.

The Census Bureau released a study discussing the changes in growth patterns since 2010. Interestingly, of the 50 fastest-growing metro areas over the last decade, only 24 were still in the top fifty since the 2010 census. Unsurprisingly, the areas most affected by the real estate boom fell out (Las Vegas, Palm Coast FL) fell out of the top 50 and it appears some of the energy-centric areas (TX, ND) are entering.

Wednesday, April 4, 2012

Morning Report

Vital Statistics:

LastChangePercent
S&P Futures 1397.8-11.0-0.78%
Eurostoxx Index2429.9-29.0-1.18%
Oil (WTI)102.74-1.3-1.22%
LIBOR0.46920.0000.00%
US Dollar Index (DXY)79.7230.2400.30%
10 Year Govt Bond Yield2.26%-0.04%
RPX Composite Real Estate Index170.610.0

Markets are continuing their sell-off that started after the Fed released the minutes of their last FOMC meeting. The message: The economy has to weaken for the Fed to consider another round of quantitative easing. Ironically, the FOMC statement noted more strength in the economy, but the markets are selling off.

A lousy Spanish bond auction has people wringing their hands over Europe again. Euro sovereign spreads are wider across the board, and Greek spreads continue to widen. Post restructuring, the Greek 10 year yield bottomed at 18% two weeks ago. It is now 22%. The ECB also kept rates unchanged at their meeting today and forecast the eurozone economy will shrink .3% this year. The ECB is in a pickle as inflation is becoming a risk in Germany while deflation is a risk in the South.

ADP released their March National Employment Report, suggesting nonfarm private employment increased by 209,000 in March. After declining for 4 years, we are seeing modest growth in construction and finance.

Steven Davidoff (The Deal Professor) lambastes the JOBS act. The punch line: Decimalization could explain why small IPOs are lagging as much as inability to access VC funds. Essentially, Congress is clueless about the financial markets (true) and legislates to the political winds (true). The reason why this bill got pushed through is so that Washington can have the appearance of "doing something" about jobs in the US. The unintended consequence is that it makes it easier for a dodgy company to raise capital, and if we have a couple of Sino Forests on our hands, multiples could contract across the market.

The WSJ has a story discussing how much credit has tightened. Loans closed in February had an average FICO of 750 and LTC of 76%. The average denied loan had a FICO of 699 and LTV of 83. 699. 83. Denied. They go on to say that even as credit conditions ease in the greater economy, credit conditions in residential mortgages are still getting tighter. Of course, this is one of the side effects of abnormally low interest rates - as a lender, you are almost guaranteed to lose money lending for 30 years at 3.75%. Unintended consequences rear their ugly head again.

Is your local savings bank becoming a credit union? If it is, perhaps it is due to the new regulatory environment. As the OTS gives way to the OCC, many smaller banks are opting to become credit unions or state regulated.

Tuesday, April 3, 2012

Morning Report

Vital Statistics:

LastChangePercent
S&P Futures1410.0-2.6-0.18%
Eurostoxx Index2486.0-15.2-0.61%
Oil (WTI)104.53-0.7-0.67%
LIBOR0.46920.0010.21%
US Dollar Index (DXY)78.9340.1140.14%
10 Year Govt Bond Yield2.16%-0.02%
RPX Composite Real Estate Index170.630.1

Equity markets are slightly lower this morning on no major news. Bonds are up half a point and MBS are up about 1/4 of a point. After spiking to 2.38%, the 10 year bond has been slowly rallying, with yields back to 2.16%.

Regulators are trying to figure out how to apply some of the terms of the landmark $25 billion settlement to other financial firms. Iowa AG Patrick Madigan fires a shot across the bow of servicers: "Loan servicing has been a mess for the past four of rive years. Reforming that industry is very important and very challenging." He goes on further to say that it isn't only the servicer / borrower relationship that he is focused on, it is also the servicer / MBS investor. Of course this helps explain why you can't give away MSRs right now. Regulators are going after another 8 banks - SunTrust, US Bancorp, PNC, EverBank, GOldman, OneWest, MetLife, and HSBC.

The $25 billion settlement included a foreclosure moratorium which kept a lot of property off the market. They are about to be released, and RealtyTrac estimates that prices could drop as much as 10 percent. Moody's estimates sales of REO will probably rise 25% this year. A lot of these properties could be 100% losses. Interesting statistic from the Federal Reserve Bank of Cleveland: Foreclosures held less than a year lose about 35%. After two years, the loss is close to 60%.

The NYT has yet another piece on institutional investors buying REOs and turning them into rentals.

The markets will be looking to the release of the FOMC meeting minutes for more clues into QEIII and what replaces Operation Twist. They should be released around 2:00 - 2:15 EST.

Monday, April 2, 2012

Morning Report

Vital Statistics:

LastChangePercent
S&P Futures1402.3-0.9-0.06%
Eurostoxx Index2455.6-21.7-0.88%
Oil (WTI)102.66-0.4-0.35%
LIBOR0.46820.0000.00%
US Dollar Index (DXY)79.0150.0110.01%
10 Year Govt Bond Yield2.20%-0.01%
RPX Composite Real Estate Index170.510.4

Stocks are flattish this morning on no real news in the US. Bonds and mortgages are up slightly. Construction Spending and ISM reports are out at 10:00 this morning. There was some disappointing economic data out of Europe - Eurozone unemployment was 10.8%, which suggests Europe is in a recession. France, Germany, and Italy Purchasing Managers Indices all came in below 50, indicating manufacturing conditions are in a decline. The Japanese Tankan survey was disappointing as well.

The Washington Post had a long article about rentals over the weekend. Big investors are using proprietary algos to analyze and manage rental properties. Oaktree, Carrington, Starwood, Apollo, and Zell are getting into this business. Private equity fund Waypoint reported a return of 8% to 9% in Q4 buying foreclosed properties and renting them. Interesting. RTWT.

Bill Gross's Total Return Fund gained 2.83% in Q1, outperforming the benchmark by 2 percentage points on an aggressive bet on mortgages. He increased the mortgage exposures from 38% in September to 52% at the end of February. This is a bet on either (a) QEIII or (b) The fed replacing Operation Twist with a more aggressive stance on mortgage purchases. In other words, mortgage rates have been pushed lower by two big behemoths - PIMCO and the Fed - aggressively buying mortgage backed securities. If the Fed doesn't provide an exit for Bill (either by not doing QEIII or not replacing Operation Twist with a mortgage support program), then mortgage rates could back up in a hurry. Something for lock desks to think about..